Avoid a $205M Error: How Analysts Verify Fully Diluted Market Cap
By MarketCapLens · Published · 9 min read
Fully diluted market cap equals the current share price multiplied by fully diluted shares outstanding, which includes common shares plus every in-the-money option, warrant, convertible bond, and convertible preferred share that could turn into stock. Analysts favor this number over basic market cap because it shows the worst-case equity value, the one an acquirer or shareholder would face if every dilutive instrument got exercised at once. The formula: Fully Diluted Market Cap = Share Price × (Basic Shares + Net Dilutive Shares from Options, Warrants, and Convertibles).
TL;DR:
- Fully diluted market cap includes only in-the-money, vested options, warrants, and convertibles, excluding out-of-the-money and unvested awards.
- The treasury stock method and the if-converted method are used to calculate the incremental share count, with anti-dilution sequencing crucial for accuracy.
- Key data for calculations are found in EPS and stock-based compensation notes within the 10-K, not just in summary tables.
- An example shows a 4.1% increase in market cap when including dilutive securities, driven mainly by options and convertible bonds.
- Properly applying anti-dilution tests and accurate share count adjustments prevent common overstatements in diluted share estimates.
MarketcaplensTrack Market Cap With More ContextMarketCapLens brings together market capitalization, share prices, historical data, and sector breakdowns across more than 2,500 public companies.Explore MarketCapLens
Table of Contents
- What Counts Toward the Fully Diluted Share Count?
- How Do You Calculate Diluted Shares From Options and Convertibles?
- Where Do You Find These Numbers in a 10-K?
- A Worked Example: Basic vs. Fully Diluted Market Cap
- What Mistakes Do Analysts Make With Dilution?
- When Should You Use Fully Diluted Market Cap in Analysis?
- How MarketCapLens Helps You Verify These Numbers
- Where to Verify the Accounting Rules Yourself
- Why Most Explainers Get Fully Diluted Market Cap Half Right
- Sources
- FAQ
What Counts Toward the Fully Diluted Share Count?
Basic market cap uses price times basic shares outstanding, the number printed on the balance sheet cover page. Fully diluted market cap starts there and adds every instrument that could convert into new stock, which is why the two figures can diverge by a wide margin for growth companies loaded with equity compensation.
The instruments that typically get added include:
- Stock options and RSUs granted to employees and executives, but only the vested, in-the-money portion
- Warrants issued to lenders, underwriters, or as part of SPAC deals
- Convertible bonds that holders can swap for equity at a set conversion ratio
- Convertible preferred stock with similar conversion terms
- Contingently issuable shares, when the underlying conditions have already been met
Two filters matter more than any other detail here. First, an instrument has to be “in the money,” meaning the current share price exceeds the option or warrant strike price. Second, for equity awards, only the vested portion counts, not the full grant. Companies also report a weighted-average share count for the period rather than a single snapshot, which matters when share issuance or buybacks happened mid-year. Get the share count wrong and every downstream multiple, from P/E to price-to-sales, comes out wrong with it.
How Do You Calculate Diluted Shares From Options and Convertibles?
Two accounting methods do the heavy lifting, and both trace back to ASC 260, the U.S. GAAP standard governing earnings per share.
- Treasury stock method (TSM) for options and warrants. The method assumes holders exercise every in-the-money option, the company collects the exercise proceeds, and then uses that cash to repurchase shares at the average market price for the period. The net dilution is the gap between shares issued and shares repurchased. A quick shortcut version: incremental shares equal the option count times (1 minus strike price divided by market price), though you should always verify against actual filing figures rather than relying on the shortcut alone.
- If-converted method for convertible debt and preferred stock. This assumes bondholders or preferred shareholders convert at the stated ratio, which adds shares to the denominator. But it also changes the numerator: since the debt no longer exists in this scenario, you add back the after-tax interest expense (or preferred dividends) to net income.
- Anti-dilution sequencing. ASC 260 requires testing instruments in a specific order, generally options first since they only touch the denominator, then convertibles since they touch both numerator and denominator. Any instrument that would increase EPS rather than reduce it gets excluded at that step, because including it would be anti-dilutive rather than dilutive.
Pro Tip: Run the sequencing test instrument by instrument, not all at once. A convertible bond can be dilutive on its own but anti-dilutive once combined with a large options tranche, and skipping the order-dependent test is one of the most common ways analysts overstate diluted share counts.
Where Do You Find These Numbers in a 10-K?
Every input you need to rebuild a fully diluted share count sits in two specific places inside the annual report, and neither one is the summary table most people skim past.
- The EPS note in Item 8 of the 10-K reconciles basic weighted-average shares to diluted weighted-average shares, line by line, showing exactly how many incremental shares came from options versus convertibles.
- The stock-based compensation note lists outstanding options and RSUs, weighted-average exercise prices, and vesting schedules, everything the treasury stock method needs.
- The balance sheet and cover page show shares outstanding as of the filing date, useful for a quick basic market cap check but not sufficient on its own for the diluted figure.
- The debt and equity notes disclose convertible bond terms, including conversion ratios and outstanding principal.
Annual 10-Ks beat quarterly 10-Qs for this work because 10-Qs often skip the detailed schedules that make the EPS note reconstructable. If you only have a mid-year 10-Q, treat the diluted figure as directional rather than final until the next annual filing confirms it.
A Worked Example: Basic vs. Fully Diluted Market Cap
Say a company trades at $50 per share with 100 million basic shares outstanding, putting basic market cap at $5 billion.
- Options tranche via TSM. The company has 4 million options outstanding with a $30 strike price. Exercise proceeds total $120 million (4 million × $30). At $50 per share, that buys back 2.4 million shares. Net dilution: 4 million issued minus 2.4 million repurchased equals 1.6 million incremental shares.
- Convertible bond via if-converted. A $100 million convertible bond converts at a ratio equivalent to 2.5 million shares. Assuming conversion, you add back the after-tax interest the company would no longer pay, adjusting net income upward for the diluted EPS calculation.
- Sum the diluted share count. Basic shares (100 million) plus TSM dilution (1.6 million) plus if-converted shares (2.5 million) equals 104.1 million fully diluted shares.
- Compute fully diluted market cap. 104.1 million shares × $50 equals $5.205 billion, roughly $205 million higher than the basic figure, a 4.1% gap driven entirely by dilutive securities.
What Mistakes Do Analysts Make With Dilution?
The most common error is treating every option grant as automatically dilutive. Out-of-the-money and unvested awards get excluded because only in-the-money, vested securities count toward the diluted share total; anything else would be anti-dilutive if forced into the math.
- Using end-of-period shares instead of the weighted-average count for the reporting period
- Skipping the anti-dilution sequencing test and including every convertible regardless of its individual effect on EPS
- Ignoring settlement terms, since some awards settle in cash rather than shares and shouldn’t be added to the share count at all
- Assuming contingently issuable shares count automatically, when they only qualify once the underlying condition is actually met by period end
Pro Tip: When a company’s options pool looks unusually large relative to its float, check the weighted-average exercise price against the current share price before assuming heavy dilution. A pool struck well above market price contributes almost nothing to the diluted count, no matter how big the headline number looks.
When Should You Use Fully Diluted Market Cap in Analysis?
Fully diluted market cap earns its place in a few specific workflows rather than as a universal replacement for the basic figure.
- Use it for conservative equity comparisons across companies with different capital structures, since it neutralizes differences in how aggressively each one has issued options or convertibles
- Reference it when assessing ownership dilution, since it shows existing shareholders the maximum percentage of the company that could get diluted away
- Pair it with diluted EPS, since diluted shares directly reduce EPS compared with the basic figure, which changes how P/E ratios and other per-share multiples read
- Present both basic and fully diluted figures side by side in any report, clearly captioned, rather than picking one and hiding the other
- Run sensitivity checks on exercise prices and conversion terms, since a stock’s climb toward in-the-money status can shift dilution meaningfully quarter to quarter
Fully diluted market cap is a measure of equity value, not enterprise value. If you’re comparing companies with different debt loads, that’s a separate calculation entirely.
How MarketCapLens Helps You Verify These Numbers
Some platforms track large numbers of public companies with data refreshed multiple times daily, covering share prices, sector breakdowns, and historical performance you’d otherwise have to pull from scattered filings. Such platforms can surface the raw inputs analysts need, historical share counts, sector context, and daily price movement, so cross-checking a diluted share calculation against current market data can be quicker than digging manually through filings.
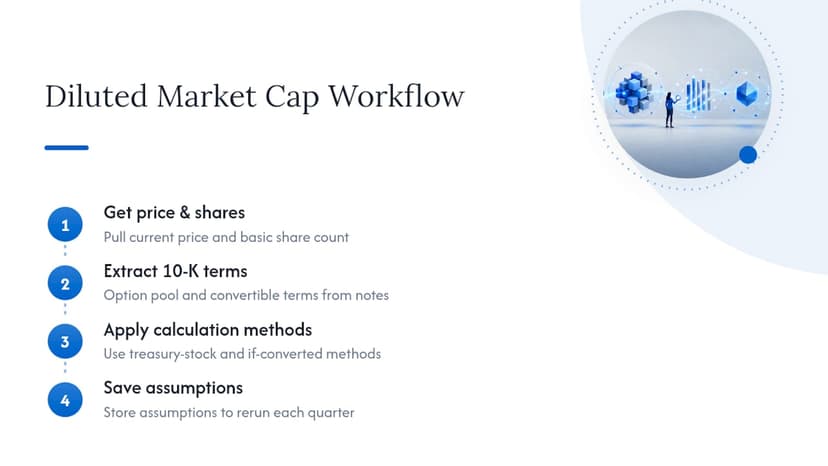
A practical workflow: pull the basic share count and current price from a reliable data source, extract the option pool and convertible terms from the 10-K’s EPS and stock-based compensation notes, apply the treasury stock and if-converted methods by hand, then save your assumptions so you can rerun the math when the next quarterly filing lands. The rankings and data pages exist specifically to make that first step, getting a reliable current price and basic share count, fast enough that the accounting work is the only part that takes real time.
Where to Verify the Accounting Rules Yourself
For primary verification, consult the SEC’s own guidance on reading 10-K disclosures, EY’s technical breakdown of ASC 260, and Corporate Finance Institute’s diluted shares reference for calculation walkthroughs.
Why Most Explainers Get Fully Diluted Market Cap Half Right
Most coverage of this topic stops at the definition and never touches the mechanics, which is exactly backward for the audience that actually needs the number. Knowing that fully diluted market cap “includes options and convertibles” doesn’t help you when you’re staring at a stock-based compensation note with six different strike price tranches and no idea which ones clear the in-the-money bar.
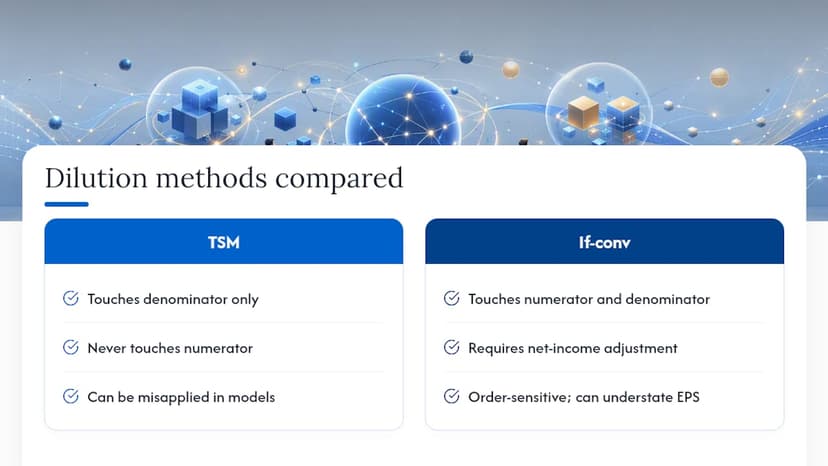
The conventional advice treats treasury stock method and if-converted method as interchangeable dilution math. They’re not. TSM only ever touches the denominator. If-converted touches both the denominator and the numerator, which means skipping the net income adjustment on a convertible bond understates diluted EPS even when the share count is right. That single distinction trips up more spreadsheet models than any other step in this process.
If you take one thing from this piece, prioritize the anti-dilution sequencing test over memorizing formulas. A company with a large options pool struck near the current price and a convertible bond with a rich coupon can produce wildly different diluted figures depending on the order you test them in, and getting that order wrong is the difference between a defensible valuation and a number nobody should trust.
— MarketCapLens
Sources
- Treasury stock method (TSM) — Wall Street Prep
- Financial reporting developments - Earnings per share — EY
- What is fully diluted market capitalization? — LegalClarity
- Diluted shares — Corporate Finance Institute
FAQ
What Is the Difference Between Basic and Fully Diluted Market Cap?
Basic market cap multiplies share price by basic shares outstanding. Fully diluted market cap adds every in-the-money option, warrant, and convertible security, producing a higher, more conservative equity value.
Does Fully Diluted Market Cap Include Out-of-the-Money Options?
No. Out-of-the-money options are excluded because exercising them would be anti-dilutive; only in-the-money, vested instruments count toward the diluted share total.
Why Does the If-Converted Method Adjust Net Income?
Assuming a convertible bond converts means the company no longer pays interest on it, so accounting rules require adding back the after-tax interest expense to net income for diluted EPS purposes.
Where Do I Find Fully Diluted Shares in a 10-K?
Look at the EPS reconciliation note in Item 8 and the stock-based compensation note, which together disclose basic-to-diluted share reconciliations, option strike prices, and vesting schedules.
Is Fully Diluted Market Cap the Same as Enterprise Value?
No. Fully diluted market cap is strictly an equity value measure. Enterprise value adds debt and subtracts cash, capturing the full capital structure rather than just diluted equity.
Recommended
For informational purposes only and is not investment advice. Do not rely on the facts, figures, ticker symbols, or other statements in this article — they may be incomplete, outdated, or incorrect, and we are not responsible for errors. See our disclaimer.